Peter Cunningham shares key wealth-building insights, emphasizing disciplined spending, long-term investing, and the evolving role of AI in wealth management.
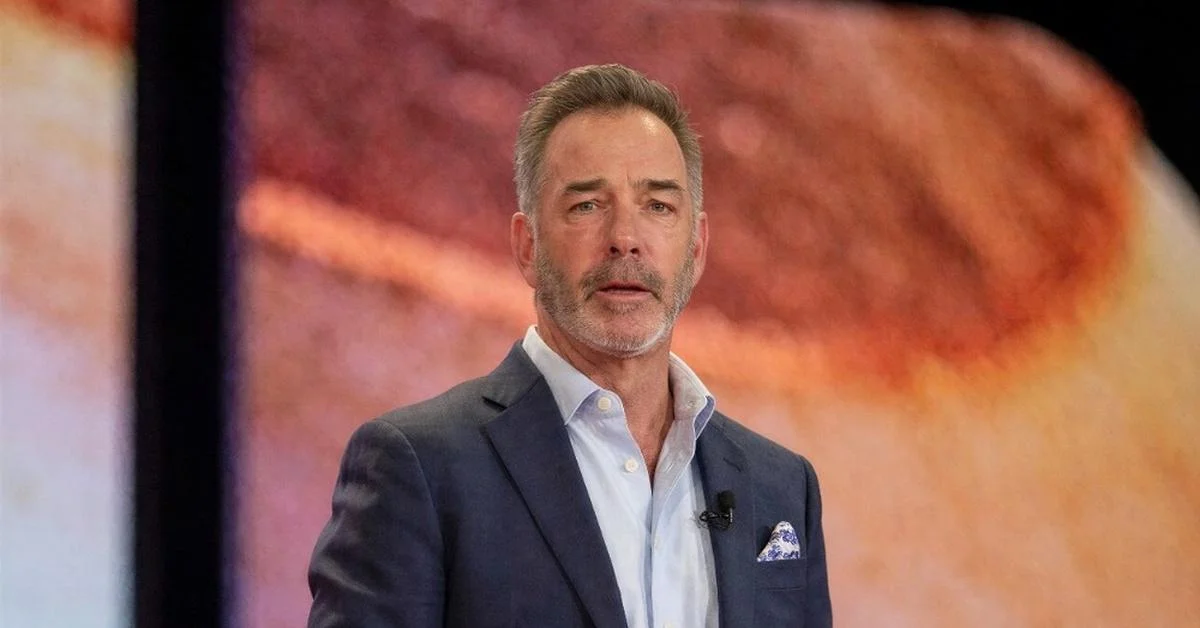
With over three decades of experience on Wall Street, wealth manager Peter Cunningham has navigated the cycles of market fluctuations, offering insights that extend beyond mere stock selection. His foundational lesson is strikingly straightforward: effective wealth building begins with controlling expenditure.
The One-Third Rule
Cunningham's unique approach involves partitioning income into three equal segments: one-third for investments, one-third for savings, and one-third for discretionary spending. While actual allocations may not look identical for each person, he underscores the importance of maintaining this discipline to foster financial growth. This straightforward formula isn’t just theoretical; it's a guideline that encourages responsible financial behavior.
For instance, consider someone earning $120,000 annually, which breaks down to about $10,000 a month before taxes. If this individual devotes the majority of that income to essential and lifestyle expenses, they risk stalling their wealth accumulation. By adopting Cunningham’s method, they could allocate roughly $2,500 to $3,000 monthly towards savings and investments instead. This powerful shift in budgeting habits can redefine one’s financial future.
The rationale for such a structured approach is anchored in the power of compounding returns. Consider this: even modest investment returns—around 7% to 8%—can yield substantial growth when those gains are allowed to accumulate over the years. The more time investments have to compound, the more impactful the results. Here’s the thing: younger investors hold a significant advantage not just in financial knowledge but in time—their greatest asset in wealth building.
Time in the Market Beats Timing the Market
This philosophy informs Cunningham’s perspective on market volatility. From his extensive experience, he’s consistently maintained that the longevity of an investment typically trumps attempts to time market fluctuations. Market downturns often stir panic, leading investors to sell at a loss, while peaks can inspire overconfidence that may not be warranted. Recognizing these emotional triggers, he advises investors to remain disciplined and avoid impulsive decisions that could jeopardize their financial health.
That said, investing strategies should flex in response to various life stages and financial needs. Younger investors who are positioned for long-term growth might consider equity-heavy portfolios, aligning with their higher risk tolerance and potential for returns. However, as one approaches retirement, shifting priorities become essential, necessitating a balanced mix of equities and fixed income securities to safeguard against market volatility. For individuals in their 70s and 80s, adopting a conservative approach that favors fixed income is often crucial for ensuring income stability and preserving capital for future needs.
AI Is Making Investors Smarter — But Advice Still Matters
The realm of wealth management is undergoing a significant transformation, with clients arriving better informed, largely due to advancements in artificial intelligence. Platforms like ChatGPT and sophisticated investing applications have democratized access to financial information that once took significant research to uncover. This evolution in the availability of data allows more potential investors to make informed decisions.
However, Cunningham sees this technological shift not as a hazard to wealth managers but as a profound transformation in their roles. Clients equipped with AI-generated analyses and investment inquiries now expect advisors to provide context and personalized insights that can help refine their decision-making process. It’s about more than just data; wealth managers have a responsibility to validate assumptions and assess how this information aligns with clients' individual financial realities.
After 35 years in the industry, Cunningham observes a substantial evolution in the tools available but maintains that the fundamental principles of wealth management remain unchanged. Key elements such as spending thoughtfully, investing regularly, adjusting investment strategies with life changes, and allowing time for investments to grow are timeless. (And this is the part most people overlook.) The basics don’t change; rather, it's how they get applied that evolves with technology.
Implications for Future Financial Management
As Cunningham’s strategies illustrate, there’s a growing recognition among both wealth managers and clients that the path to financial success is paved with discipline, patience, and adaptability. This suggests that individuals at different life stages should remain conscious and proactive about how they manage their finances. If you're working in this space, the challenge is clear: balancing traditional wealth management principles with the modern capabilities provided by technology will be essential.
Ultimately, this means that emerging and seasoned investors alike will need to understand the integration of AI in their financial strategies while remaining grounded in the timeless tenets of investing. Going forward, the wealth management industry could very well witness a shift in focus from merely managing money to also empowering clients to leverage information—ensuring that they grow more than just their financial acumen but their financial literacy as well. The numbers here are underwhelming only if participants fail to adapt to both new tools and the underlying principles of successful investing.
Discussion
Sign in to join the discussion.